You’re drowning in debt and desperately searching for a lifeline. The constant worry about money, especially with the rising cost of living in Bangladesh, has taken over your life—affecting your sleep, relationships, and mental wellbeing. I hear you. Debt can feel like quicksand; the harder you struggle, the deeper you sink.
But here’s the reality: 2026 offers new opportunities, strategies, and tools to help you break free from debt’s crushing grip faster than you might think. As an AI analyzing current financial trends, I can tell you that getting out of debt requires a structured plan, not a get-rich-quick scheme.
Whether you’re dealing with high-interest credit card debt, personal bank loans, borrowing from relatives, or microfinance obligations, this SEO-friendly guide is designed to help you create a roadmap to financial freedom in today’s Bangladeshi economic climate.
The Debt Landscape in Bangladesh: Why 2026 Requires a New Approach
The growing middle class in Bangladesh has seen a surge in access to credit cards and personal loans. Combined with recent inflationary pressures on daily commodities and housing in cities like Dhaka and Chattogram, many households are finding a larger portion of their monthly income consumed by EMIs (Equated Monthly Installments).
Here’s why getting out of debt in 2026 requires a focused approach:
Fluctuating Interest Rates: With Bangladesh Bank adjusting monetary policies and market-based interest rates, loan costs have changed.
Digital Lending & MFS: Mobile Financial Services (like bKash, Nagad) and digital nano-loans have made borrowing easier—but also easier to lose track of.
The Gig Economy Boom: Freelancing, f-commerce (Facebook businesses), and ride-sharing platforms have expanded income-boosting possibilities.
CIB Report Importance: A clean Credit Information Bureau (CIB) report is more crucial than ever for future financial stability.
Research consistently shows that those who follow structured debt elimination plans are nearly three times more likely to become debt-free than those who tackle it haphazardly.
Step 1: Face Your Financial Reality (The Crucial First Move)
Before diving into specific strategies, you need to confront the full extent of your debt. It’s impossible to navigate out of a maze while blindfolded.
Create Your Complete Debt Inventory
Open a spreadsheet or grab a notebook and list every single debt you owe:
Creditor name: (e.g., BRAC Bank, City Bank, a relative, an NGO)
Current balance: (Total amount owed in BDT)
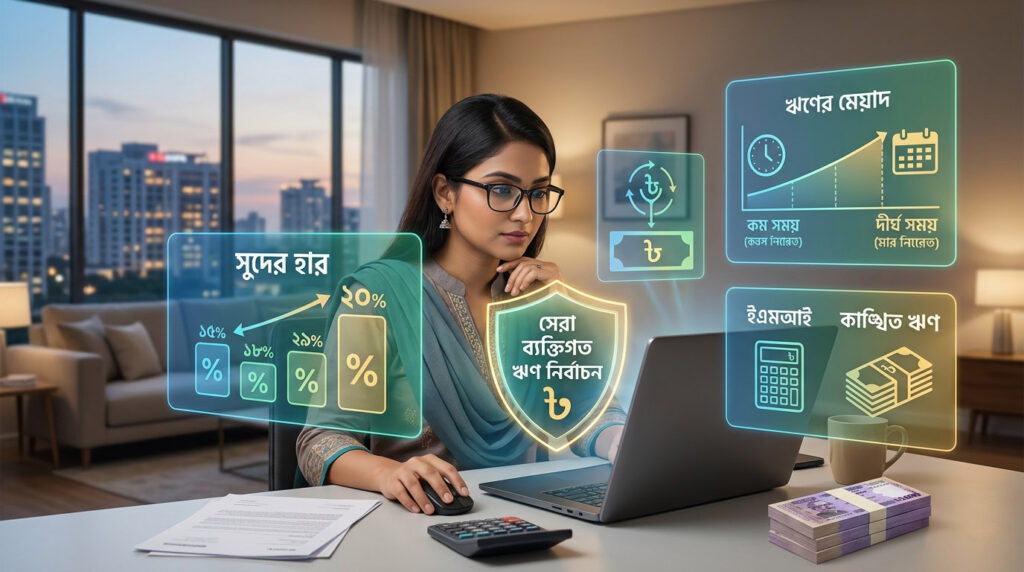
Interest rate: (The percentage you’re being charged)
Minimum monthly EMI/Payment
Due date
Debt type: (Credit card, auto loan, personal loan, etc.)
Financial experts often note that people are shocked to discover they are paying 20% or more on credit card debt while focusing all their extra cash on a 9% car loan. This simple inventory immediately highlights where you are losing money.
Calculate Your Debt-to-Income (DTI) Ratio
Lenders use this to evaluate your financial health. To calculate it:
Add up all your monthly debt payments (EMIs).
Divide by your gross monthly income.
Multiply by 100 to get a percentage.
(Example: If you pay ৳20,000 monthly toward debts and earn ৳50,000 monthly, your DTI is 40%.)
Before focusing on debt payoff, you must stop accumulating more. You cannot empty a bucket if the tap is still running.
Create a Zero-Based Budget
Assign every Taka of your income a specific job until you reach zero unallocated funds.
List all income sources for the month.
List all required expenses (house rent, groceries, utility bills, minimum debt payments).
Allocate remaining funds to additional debt payments, savings (like a DPS), and discretionary spending.
The “Cash Diet” Challenge
In an era where scanning a QR code on your phone takes two seconds, try using physical cash (কাঁচা টাকা) for all discretionary spending for 30 days. People spend significantly less when using physical cash because of the psychological “pain” of parting with tangible money.
Eliminate Financial Leaks
Audit your recurring expenses:
Multiple OTT platforms (Netflix, Hoichoi, Chorki) when you only watch one.
Excessive food delivery (Foodpanda/Pathao Food) instead of cooking at home.
Unused gym memberships.
Step 3: Choose Your Debt Elimination Strategy
With new debt halted, choose a systematic approach to eliminate existing debt.
The Avalanche Method: Mathematically Optimal
Direct extra payments toward the highest-interest debt first while making minimum EMIs on everything else.
Pros: Saves the most money in interest; fastest total payoff time.
Cons: Can be demotivating if the high-interest debt is massive and takes a long time to clear.
Sample Bangladeshi Debt Profile:
Debt Type
Balance (BDT)
Interest Rate
Minimum EMI (BDT)
Credit Card A
৳45,000
20.0%
৳2,500
Personal Loan
৳150,000
11.5%
৳4,000
Credit Card B
৳15,000
18.0%
৳1,000
Car Loan
৳800,000
9.0%
৳15,000
Using the Avalanche Method, you would target Credit Card A first, then Credit Card B, followed by the Personal Loan, and finally the Car Loan.
The Snowball Method: Psychologically Powerful
Focus on quick wins by paying off the smallest balances first, regardless of interest rates.
Pros: Creates highly motivating early wins; simplifies finances faster.
Cons: Usually costs more in total interest over time.
Using the Snowball Method, the order would be: Credit Card B (৳15,000) -> Credit Card A (৳45,000) -> Personal Loan -> Car Loan.
Step 4: Accelerate Payoff with Income Boosting
In Bangladesh’s evolving economy, increasing your income can dramatically accelerate your debt elimination.
Leverage Your Primary Job: Ask for overtime, or negotiate for non-salary benefits like transport allowances or lunch subsidies.
The Gig Economy: Bangladesh is a global hub for freelancing. Utilize platforms like Upwork or Fiverr if you have digital skills (graphics, coding, writing).
Local Side Hustles: Utilize Pathao or Uber if you own a bike or car. Offer private tuitions, which remain a highly lucrative and reliable side income in Bangladesh.
F-Commerce: Sell homemade goods, clothing, or baked items through Facebook or Instagram.
Step 5: Debt Consolidation and Refinancing
Strategic restructuring can lower interest rates.
Balance Transfers: Some Bangladeshi banks offer balance transfer facilities to move high-interest credit card debt to a lower-interest EMI plan. Always check the processing fees.
Liquidating a DPS Early: While breaking a Deposit Pension Scheme (DPS) or FDR early means losing out on some interest, using that cash to clear a 20% interest credit card is almost always mathematically the smarter move.
Personal Consolidation Loans: Taking a single 10-12% personal loan to clear multiple high-interest debts can simplify your life, but only if you stop using the credit cards immediately afterward.
Step 6: Negotiate with Creditors
Many people avoid talking to their banks out of fear, but financial institutions prefer negotiation over default (which ruins your CIB report and causes them to lose money).
EMI Restructuring: If you are facing genuine financial hardship (like a job loss), approach your bank to restructure your loan for a longer tenure with a lower EMI.
Credit Card Settlement: If a card is severely delinquent, banks will sometimes negotiate a waiver on the accrued penal interest if you can offer a lump-sum payment to clear the principal amount.
Step 7: Protect Your Progress with Strategic Habits
Getting out of debt is an achievement; staying out requires resilience.
Build an Emergency Fund: Aim for at least ৳10,000 – ৳20,000 in a liquid savings account or mobile wallet immediately, then build toward 3 months of living expenses. This stops you from swiping a credit card when a medical emergency or urgent home repair pops up.
Automate Savings: Set up a DPS that automatically deducts from your salary account on the 2nd of every month. If you don’t see the money, you won’t spend it.
Real-World Debt Elimination Scenarios
Let’s look at how these strategies apply to real Bangladeshi scenarios:
Tariq & Nipa: Cleared ৳6 Lakh in 20 Months
Strategy: Used the Debt Snowball method.
Action: Sold their private car to clear a massive chunk of their auto loan and switched to Metro Rail and ride-sharing. Nipa started an online catering business (f-commerce) on weekends, directing 100% of those profits toward their remaining personal loans.
Hasan: Eliminated ৳2.5 Lakh Credit Card Debt
Strategy: Consolidation and Leaks.
Action: Hasan realized his habit of eating at expensive cafes in Banani every weekend was costing him ৳15,000 a month. He cut this out entirely, broke a low-yield FDR, and paid off his high-interest credit card in one go, avoiding a debt trap.
Conclusion: Your Debt-Free Future Starts Today
Breaking free from debt isn’t just about the numbers—it’s about reclaiming your peace of mind and securing your family’s future.
Take inventory of everything you owe.
Stop new borrowing.
Pick a strategy (Avalanche or Snowball).
Boost your income.
Stay consistent.
The journey to a debt-free life in Bangladesh will have its challenges, but the financial freedom waiting on the other side is worth every sacrifice.
আপনি কি ঋণের চাপে দিশেহারা? প্রতি মাসের কিস্তি আর সুদের দুশ্চিন্তায় কি আপনার রাতের ঘুম হারাম হয়ে যাচ্ছে? বিশ্বাস করুন, আপনি একা নন। আমাদের দেশে ক্রমবর্ধমান জীবনযাত্রার ব্যয় এবং মুদ্রাস্ফীতির এই সময়ে অনেকেই অনিচ্ছাসত্ত্বেও ঋণের জালে জড়িয়ে পড়ছেন। ঋণ অনেকটা চোরাবালির মতো—যত বেশি ছটফট করবেন, তত গভীরে তলিয়ে যাবেন। কিন্তু আশার কথা হলো, ২০২৬ সালে এই আমেরিকা-ইজরায়েল ও ইরান যুদ্ধের বিভীষিকাময় অবস্থায় দাঁড়িয়েও আমাদের হাতে এমন কিছু কৌশল ও প্রযুক্তি আছে, যা ব্যবহার করে আপনি এই ঋণের বোঝা থেকে দ্রুত মুক্তি পেতে পারেন। এই গাইডে আমরা কোনো অবাস্তব স্বপ্ন দেখাব না, বরং বাংলাদেশের বাস্তবতায় কার্যকর কিছু পদক্ষেপ নিয়ে আলোচনা করব।
বাংলাদেশে বর্তমান ঋণ পরিস্থিতি: কেন ২০২৬ সাল ভিন্ন?
বাংলাদেশে বর্তমানে ব্যাংক লোন, ক্রেডিট কার্ড এবং বিশেষ করে বিভিন্ন ক্ষুদ্রঋণ (Micro-credit) ও অ্যাপ-ভিত্তিক ঋণের প্রকোপ বেড়েছে। আগে মানুষ শুধু বড় প্রয়োজনে ঋণ নিত, কিন্তু এখন দৈনন্দিন খরচ মেটাতেও অনেকে ক্রেডিট কার্ড বা পার্সোনাল লোনের ওপর নির্ভরশীল হয়ে পড়ছেন। এছাড়া আমেরিকা-ইজরায়েল ও ইরান যুদ্ধের কারনে সারা বিশ্বে একটা অর্থনৈতিক মন্দা বিরাজ করছে।
২০২৬ সালে কেন নতুন কৌশলের প্রয়োজন?
সুদের হারের পরিবর্তন: বাংলাদেশ ব্যাংকের নতুন নীতিমালার কারণে ঋণের সুদের হারে বড় পরিবর্তন এসেছে। ডিজিটাল ব্যাংকিং: মোবাইল ব্যাংকিং (বিকাশ/নগদ) ও ডিজিটাল ন্যানো লোন পাওয়ার সুযোগ যেমন বেড়েছে, তেমনি এর উচ্চ সুদ ঋণের ফাঁদও তৈরি করছে। ফ্রিল্যান্সিং ও সাইড ইনকাম: প্রযুক্তির কল্যাণে মূল চাকরির পাশাপাশি বাড়তি আয়ের সুযোগ এখন আগের চেয়ে অনেক বেশি। ধাপ ১: আর্থিক বাস্তবতার মুখোমুখি হন (প্রথম ও প্রধান কাজ) আপনার কত টাকা ঋণ আছে তা পরিষ্কারভাবে না জানা পর্যন্ত আপনি তা থেকে মুক্তি পাবেন না। এটি অনেকটা ম্যাপ ছাড়া গন্তব্যে পৌঁছানোর চেষ্টার মতো।
একটি ঋণের তালিকা (Inventory) তৈরি করুন
একটি খাতা বা এক্সেল শিটে নিচের তথ্যগুলো লিখে ফেলুন: পাওনাদারের নাম: (কোন ব্যাংক, বন্ধু বা এনজিও) মোট পরিমাণ: (বর্তমানে কত টাকা বাকি আছে) সুদের হার: (শতকরা কত টাকা সুদ দিচ্ছেন) মাসিক কিস্তি: (প্রতি মাসে সর্বনিম্ন কত টাকা দিতে হয়) শেষ তারিখ: (কবে নাগাদ লোন শেষ হবে)
আপনার ঋণ ও আয়ের অনুপাত (DTI) বের করুন
আপনার মোট মাসিক ঋণের কিস্তিকে মাসিক মোট আয় দিয়ে ভাগ করুন এবং ১০০ দিয়ে গুণ করুন। ৩০%-এর নিচে: আপনার ঋণ নিয়ন্ত্রণে আছে। ৩০-৪৩%: চিন্তার বিষয়, এখনই সাবধান হতে হবে। ৪৩%-এর উপরে: আপনি বিপদে আছেন, জরুরি পদক্ষেপ প্রয়োজন।
ধাপ ২: নতুন করে ঋণ নেওয়া বন্ধ করুন
বালতি ছিদ্র থাকলে যেমন জল ভরা যায় না, তেমনি নতুন ঋণ নেওয়া বন্ধ না করলে পুরনো ঋণ শোধ করা অসম্ভব। 'জিরো-বেজড' বাজেট করুন আপনার আয়ের প্রতিটি টাকার হিসাব আগে থেকেই ঠিক করে রাখুন। বাড়ি ভাড়া, বাজার খরচ ও বিদ্যুত বিলের পর যে টাকা থাকবে, তা সরাসরি ঋণের কিস্তিতে দেওয়ার পরিকল্পনা করুন। 'ক্যাশ ডায়েট' চ্যালেঞ্জ আগামী ৩০ দিন ক্রেডিট কার্ড বা মোবাইল ব্যাংকিংয়ের বদলে শুধু নগদ টাকায় কেনাকাটা করার চেষ্টা করুন। গবেষণায় দেখা গেছে, মানুষ যখন হাতে নগদ টাকা গুনে খরচ করে, তখন কার্ডের তুলনায় ১২-১৮% খরচ কম হয়। ফালতু খরচ খুঁজে বের করুন ওটিটি সাবস্ক্রিপশন (Netflix/Hoichoi), বাইরে রেস্টুরেন্টে খাওয়া বা অপ্রয়োজনীয় অনলাইন শপিং—এই ছোট ছোট খরচগুলো বন্ধ করলে মাসে বেশ বড় একটা অংক সাশ্রয় করা সম্ভব।
ধাপ ৩: ঋণ পরিশোধের কৌশল বেছে নিন
দুটি জনপ্রিয় পদ্ধতির মধ্যে আপনার জন্য যেটি সহজ, সেটি বেছে নিন: ১. অ্যাভালাঞ্চ পদ্ধতি (Avalanche Method): এখানে আপনি যে ঋণের সুদ সবচেয়ে বেশি, সেটি আগে শোধ করবেন। এটি গাণিতিকভাবে লাভজনক কারণ এতে আপনার সুদের খরচ সবচেয়ে বেশি কমে। ২. স্নোবল পদ্ধতি (Snowball Method): এখানে আপনি সুদের হার না দেখে সবচেয়ে ছোট অংকের ঋণটি আগে শোধ করবেন। এতে দ্রুত একটি ঋণ শেষ হওয়ার মানসিক শান্তি পাবেন, যা আপনাকে পরের বড় ঋণটি শোধ করতে উৎসাহ দেবে।
ধাপ ৪: বাড়তি আয়ের চেষ্টা করুন
শুধুমাত্র খরচ কমিয়ে সবসময় ঋণ শোধ করা যায় না। ২০২৬ সালের এই সময়ে বাংলাদেশে বাড়তি আয়ের অনেক সুযোগ রয়েছে: স্কিল শেয়ারিং: আপনি যদি শিক্ষকতায় ভালো হন তবে টিউটরিং করতে পারেন, অথবা গ্রাফিক ডিজাইন, কন্টেন্ট রাইটিং বা ডাটা এন্ট্রির মতো ফ্রিল্যান্সিং কাজ করতে পারেন। অব্যবহৃত সম্পদ: আপনার বাসায় এমন কিছু আছে যা কাজে লাগে না? ফেসবুক মার্কেটপ্লেস বা বিক্রয় ডটকমে তা বিক্রি করে দিন। সেই টাকা সরাসরি ঋণের কিস্তিতে জমা দিন।
ধাপ ৫: ব্যাংকের সাথে আলোচনা করুন (Negotiation)
অনেকেই লজ্জায় ব্যাংকের সাথে কথা বলতে চান না। কিন্তু মনে রাখবেন, ব্যাংক আপনার টাকা ফেরত চায়, আপনার বিরুদ্ধে মামলা করা তাদের মূল লক্ষ্য নয়। লোন রিশিডিউলিং: ব্যাংকে গিয়ে ম্যানেজারের সাথে কথা বলুন। আপনার সমস্যার কথা জানিয়ে মাসিক কিস্তি কমানোর বা সময় বাড়িয়ে নেওয়ার অনুরোধ করুন। সুদ মওকুফ: অনেক সময় এককালীন বড় অংক পরিশোধ করলে ব্যাংক সুদের কিছুটা অংশ মওকুফ করতে রাজি হয়।
ধাপ ৬: আপদকালীন তহবিল (Emergency Fund) তৈরি করুন
ঋণ শোধ করার পাশাপাশি অন্তত ১০-২০ হাজার টাকা আলাদা করে রাখুন ছোটখাটো বিপদের জন্য। তা না হলে কোনো মেডিকেল ইমার্জেন্সি বা জরুরি প্রয়োজনে আপনাকে আবার নতুন করে ঋণ নিতে হবে।
সফলতার গল্প: বাস্তব উদাহরণ
কেস স্টাডি: ঢাকার একজন বেসরকারি চাকরিজীবী সোহেল সাহেবের (কাল্পনিক নাম) দুটি ক্রেডিট কার্ড ও একটি পার্সোনাল লোন মিলিয়ে প্রায় ৫ লাখ টাকা ঋণ ছিল। তিনি 'স্নোবল' পদ্ধতি অনুসরণ করে প্রথমে ক্রেডিট কার্ডের ছোট ঋণটি শোধ করেন। এরপর সেই কিস্তির টাকা বাঁচিয়ে পার্সোনাল লোনে বাড়তি পেমেন্ট দেওয়া শুরু করেন। পাশাপাশি অবসরে অনলাইনে কাজ করে মাসে বাড়তি ১০ হাজার টাকা আয় করতে শুরু করেন। মাত্র ২০ মাসে তিনি সম্পূর্ণ ঋণমুক্ত হন।
উপসংহার: আপনার ঋণমুক্ত জীবন আজ থেকেই শুরু হোক
ঋণমুক্ত হওয়া কেবল অংকের হিসাব নয়, এটি একটি মানসিক লড়াইও বটে। ২০২৬ সালের এই নতুন বছরে নিজের ভবিষ্যৎ সুরক্ষিত করতে আজই একটি পরিকল্পনা নিন। হয়তো শুরুতে কষ্ট হবে, কিন্তু ঋণের বোঝা যখন ঘাড় থেকে নেমে যাবে, সেই মানসিক প্রশান্তি হবে অমূল্য। আপনার প্রথম পদক্ষেপ কী হবে? আপনি কি আজই আপনার ঋণের তালিকা তৈরি করবেন? নাকি আগামীকালই ব্যাংকের সাথে কথা বলতে যাবেন?