কিভাবে সেরা ব্যক্তিগত ঋনটি আপনি বেছে নিবেন। Selecting the best personal loan!

ব্রাক ব্যাংকের পার্সোনাল লোন | Brac Bank Personal Loan
April 15, 2026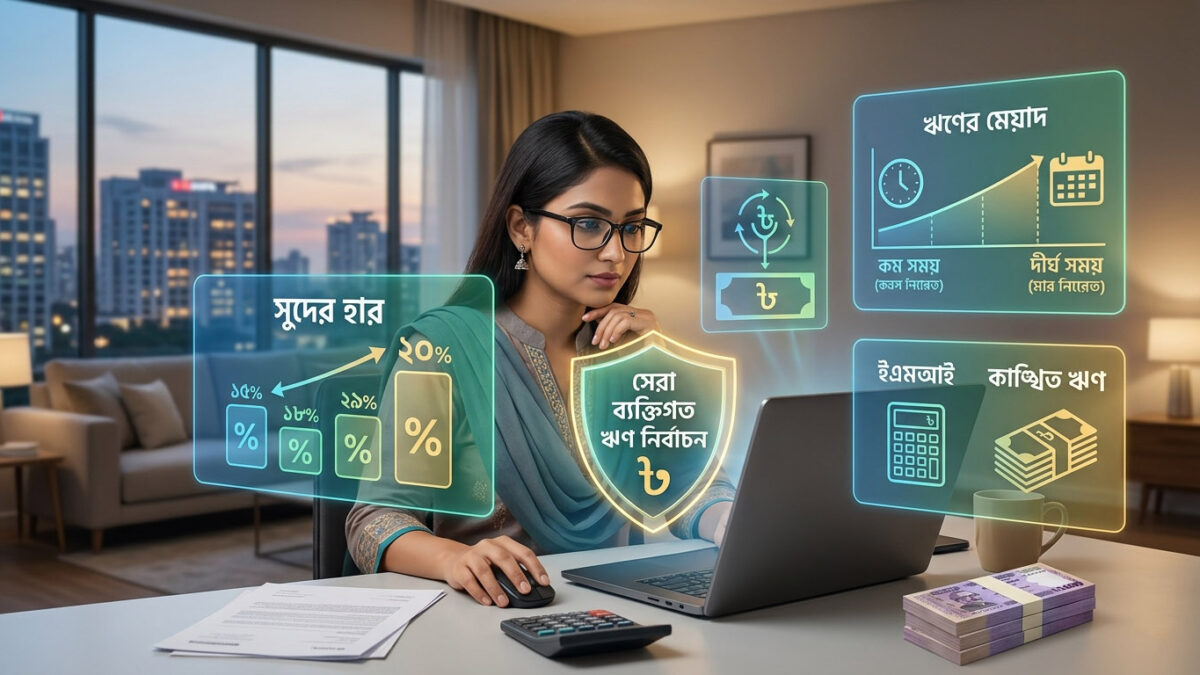
জরুরী আর্থিক প্রয়োজন মেটানোর জন্য ব্যক্তিগত ঋণ একটি সহজতর সমাধান হয়ে উঠেছে। তারপরেও ঋণগ্রহীতাকে কিছু বিষয় মাথায় রেখে সবথেকে ভালো ব্যক্তিগত ঋণের চুক্তিটি করা উচিত। ব্যক্তিগত ঋণের ক্ষেত্রে বেশ কয়েকটি বিষয় রয়েছে যার উপরে আপনি দীর্ঘমেয়াদে কতটা টাকা সুদে আসলে প্রদান করবেন তা নির্ভর করে। এসব বিষয়গুলো বিবেচনা করে ঋণদাতার সাথে মুলামুলি করলে আপনি বেশ কিছু টাকা সাশ্রয় করতে পারবেন যেগুলো আপনার প্রয়োজনে অন্যত্র কাজে লাগতে পারে।
সুদের হার:
ব্যক্তিগত ঋণের ক্ষেত্রে সবচেয়ে বড় আঘাতটি হচ্ছে সুদের হার। অন্যান্য ধরনের ঋণের থেকে ব্যক্তিগত ঋণের সুদের হার যদি তুলনা করেন তাহলে দেখবেন যে ব্যক্তি গত ঋণে সুদের হার অনেক বেশি, যা কিনা প্রায় ১৫% থেকে ২৫% হয়ে থাকে। অনেক ক্ষেত্রে ঋণগ্রহীতার অল্প পরিমাণের নির্দিষ্ট সুদের হার, অথবা বেশি সুদের হার কিন্তু পরবর্তীতে বাকি টাকা কমে গেলে সুদের হার কমবে এই ধরনের সুযোগ থাকে। আপনি হিসাব করে দেখবেন যে আপনার যেভাবে সুবিধা হয় সেই ভাবে ঋণদাতার সাথে চুক্তি করবেন।
ঋণের পরিমাণ:
ঋণের পরিমাণ নির্ধারিত হওয়ার আগে প্রথমে নির্ধারণ করা হয় যে আপনি প্রত্যেক মাসে কত টাকা ইএমআই জমা দিতে পারবেন। তারপরে আপনি যতদিন ধরে ঋণের টাকা জমা দিতে চান তার সাথে ইএমআই হিসাব করে আপনার ঋণের পরিমাণ নির্ধারণ করা হয়। আপনি যদি আগে থেকেই কত টাকা ইএমআই দিতে পারবেন এবং কাঙ্খিত ঋণ নিতে আপনার কতদিন ধরে ইএমআই পরিশোধ করতে হবে তা আগের থেকে হিসাব করে রাখেন তবে আপনার ঋণ আবেদনের সময় সুবিধা হবে।
ঋণের মেয়াদ:
যখন আপনি প্রতি মাসে কত টাকা হারে কিস্তি দিতে পারবেন তা নির্ধারন করা হয়ে যায়, তারপরে ঋণের মেয়াদ ঠিক করা হয়। সব সময় মাথায় রাখবেন যে যত কম সময়ে ঋণের মেয়াদ নির্ধারণ করা যায় ততই আপনার জন্য ভালো কারণ তাহলে আপনি সর্বসাকুল্যে কম টাকা সুদের জন্য দিবেন।
ফি এবং অন্যান্য চার্জ:
যেকোনো ঋণ প্রদান করার সময় ঋণদাতা একটি চার্জ কেটে রাখে। এই চার্জ ঋণ প্রসেসিং ফি এবং অন্যান্য ফি মিলে তৈরি হয়। আপনি সবসময় চেষ্টা করবেন যে যতটা সম্ভব এই চার্জ কমানো যায়। অনেক সময় বিভিন্ন উৎসব বা ব্যাংকের অফারে প্রসেসিং ফি ছাড়া অথবা ছাড়ে ঋণ প্রদান করে থাকে। প্রয়োজনে এরকম কখনো সুযোগ নিন। একটা কথা মনে রাখবেন আপনার প্রসেসিং ফি হিসেবে যে টাকা ব্যাংক ধরবে, আপনি ঋণ হাতে পাওয়ার আগেই সেই টাকা আপনার থেকে কমে যাবে এবং ওই টাকার উপরে আপনাকে পুরো সময় ধরে সুদ দিতে হবে।
ব্যক্তিগত ঋণের ক্ষেত্রে ঋণদাতা সাথে দর-কষাকষির সময় এই ব্যাপার গুলো মাথায় রেখে আলোচনা করবেন। আশা করি আপনি আপনার জন্য সবথেকে সেরা অফার টি বেছে নিতে পারবেন।